
Fix-and-Flip Loans for Investors Buying Properties to Renovate
Buying the worst house on the block takes a different kind of loan. Here's how renovation financing is underwritten, funded and priced — so the project finishes on budget.
By Saman Khanian
Mortgage Professional
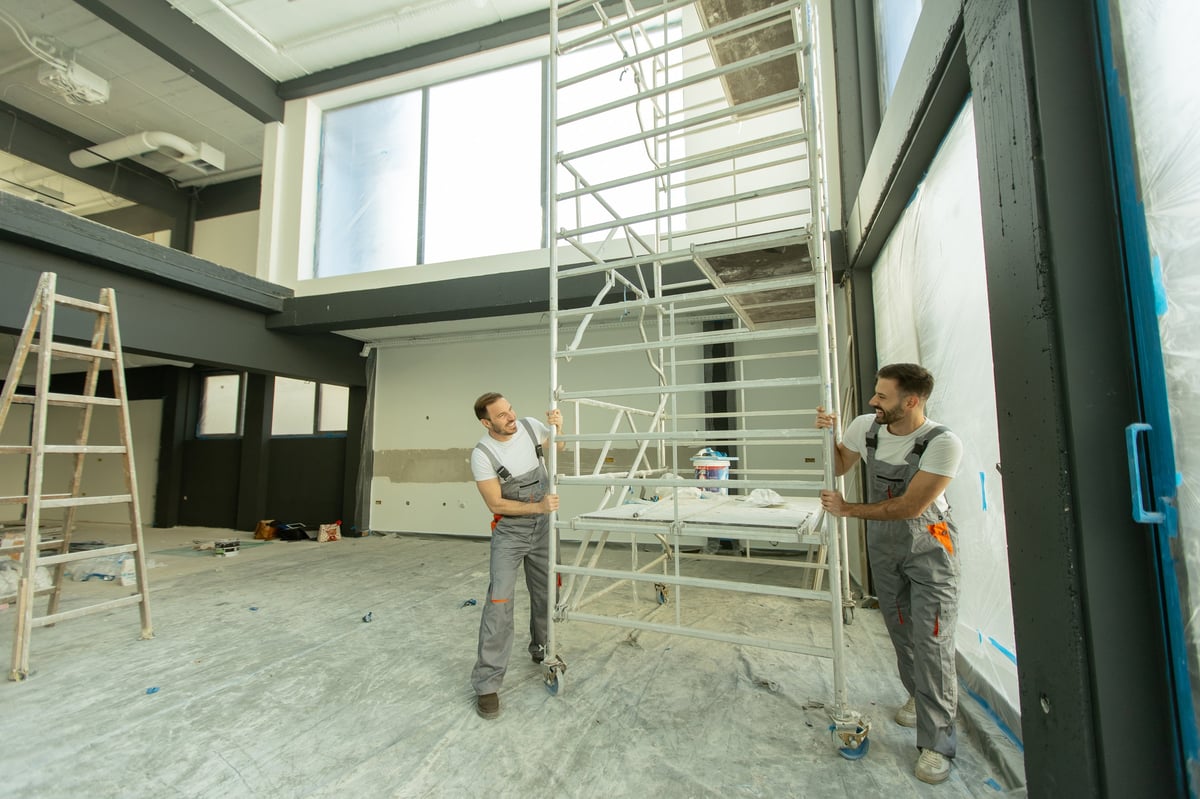
Buy, renovate, exit — financed in stages
How flip loans work
A short loan for a rushed house.
Fix-and-flip loans — often called hard money or bridge loans — are short-term, interest-only loans used to buy a property and fund its renovation. They're designed for speed and flexibility, not for holding.
What makes them different is that the lender cares most about the property's after-repair value (ARV) and how much you're putting in. The exit matters as much as the loan: a flip that sells will repay it quickly, and a property that doesn't sell usually needs a refinance into a rental loan.
Because speed and risk both increase, rates and fees are much higher than a conventional mortgage. The question isn't whether they're affordable — it's whether your spread between purchase, rehab and ARV is thin enough to justify the cost.
Rehab draws
The renovation money comes in stages
Flip lenders rarely hand over the rehab budget upfront. Funds are released in draws as work is completed and inspected — which protects the lender and keeps the project on a real timeline.
- 1
Scope of work
You submit a detailed budget, line by line, for what the renovation includes. Lenders use it to validate the rehab figure in the deal.
- 2
Initial funding
At closing, the loan funds the purchase. Rehab money is usually held back rather than released all at once.
- 3
Draw requests
As each phase of work is finished, you request a draw. Most lenders send an inspector to confirm progress before releasing funds.
- 4
Final draw & exit
Once the project is complete and inspected, the final draw is released. Then you sell or refinance into a long-term loan.
Budget honestly
Contractors who under-budget rarely finish on time. A realistic scope with a contingency line is treated far better by lenders — and by your profit margin.
Financing options
Six renovation financing paths
Typical structures. Terms, leverage and costs vary widely by lender, property and experience level.
Hard Money Loan
- Best for
- Fast closes, distressed property
- Typical term
- 6–24 months
The classic flip loan. Asset-based underwriting, fast funding, higher rates and points. Best when speed beats cost.
Bridge Loan
- Best for
- Buying before an existing sale
- Typical term
- 6–24 months
Short-term financing that bridges the gap between a purchase and the next stage, including light renovation work.
Purchase + Rehab Draw
- Best for
- Budget-controlled renovations
- Typical term
- 12–24 months
A single loan that covers the purchase and funds the rehab in inspection-based draws.
Cash-Out Flip Refinance
- Best for
- You already own the property
- Typical term
- 12–24 months
Refinance an owned property to pull equity out for renovation. Similar underwriting to a purchase flip loan.
Fix-to-Rent (DSCR Bridge)
- Best for
- Flip that becomes a rental
- Typical term
- 12–24 months
Renovation financing with a planned refinance into a DSCR rental loan. Ideal for the buy, renovate, hold strategy.
Construction Loan
- Best for
- Ground-up or major structural work
- Typical term
- 12–24 months
For heavy construction or expansion beyond a cosmetic flip. More documentation, more inspections.
Have a property in mind? Send the address and your scope of work — we'll price the project.
Apply NowQualification
What flip lenders look at — and what they ignore
Hard money underwriting is not the same as a bank mortgage. The property and the project matter more than your salary — but not everything else is ignored.
After-repair value
The lender's valuation of the finished property drives the whole deal — it sets the leverage and the maximum loan.
Experience
Experienced flippers often get better terms. First-timers may need more down payment, a contractor on the team or a lender experienced with new investors.
Cash reserves
Lenders want proof you can cover closing costs, overruns and holding costs. A reserve cushion is frequently required.
Credit
Hard money underwriting is asset-focused, but most lenders still check credit. A clean profile unlocks better pricing.
Scope of work
A detailed, realistic renovation budget with a licensed contractor estimate makes the deal far easier to underwrite.
Exit strategy
Selling within the loan term, or refinancing into a rental loan, must be credible. Lenders want to see the plan.
Running the numbers
The 70% rule, and where it falls short
A common heuristic is to keep total cost — purchase plus renovation — at or below 70% of after-repair value. It's a useful first filter, not a law of nature. Hot markets, heavy renovation and financing costs can all change the math.
What matters is the true total: purchase price, rehab budget with contingency, loan fees, points, holding costs, insurance, taxes and the cost of selling.
A deal that looks fine at 70% of ARV can break even once real costs arrive. Run every expense, then run it again with a 10% renovation overrun.
Illustrative deal
- Purchase price
- $400,000
- Renovation budget
- $80,000
- After-repair value (ARV)
- $540,000
- Loan at 75% of ARV
- $405,000
- Total project cost
- $480,000
- Estimated profit*
- ≈ $60,000
*Illustrative only, before fees, holding costs, taxes and selling costs. Not financial advice or a guarantee of profit.
Apply NowCost & trade-offs
What a fix-and-flip loan really costs
Fair comparison, not a pitch. The speed you pay for is only valuable if the margin justifies the cost.
What it gains you
- Fast closings that win competitive offers
- Financing for properties banks won't touch
- Rehab funds included in the loan
- Asset-based underwriting — your project driving the deal
- Interest-only payments protect cash flow
- Can convert to a rental loan if you choose to hold
What it costs you
- Higher rates, points and origination fees
- Short terms mean real exit pressure
- Rehab draws are inspection-based and staged
- Contingency and overruns are on you
- Holding costs accumulate if the project stalls
- A weak market can break the profit margin
Budget for the things that go wrong. Every flip has surprises — permits, hidden damage, material delays. A contingency of at least 10% plus a schedule buffer is standard practice among experienced flippers.
Frequently asked questions
What flippers ask us most.
Written by
Saman KhanianMortgage professional at Equitable Lending, helping investors finance purchases, renovations and portfolio growth across Los Angeles and nationwide.
Found the property? Let's price the project.
Send us the address, purchase price and your renovation plan. We'll tell you what leverage is realistic, what the loan will cost and how the exit can work.
Free, no-obligation review · NMLS 1124483 · DRE 01941713